Edward Conard

Top Ten New York Times Bestselling Author

  • “…a very valuable contribution.” - Larry Summers, former Secretary of the Treasury and director of the National Economic Council, president emeritus, Harvard University
  • “A full-throated defense of economic dynamism.” - The Wall Street Journal
  • “…a fresh argument for the productive value of inequality.” - David Autor, Professor of Economics, Massachusetts Institute of Technology
  • “Unintended Consequences represents the most cogent and persuasive analysis of the Financial Crisis to date.” - Andrei Shleifer, 1999 John Bates Clark Medal Winner
  • “…challenges misconceptions that distort our economic debates.” - Arthur Brooks, President of the American Enterprise Institute
  • “…a fresh argument for the productive value of inequality.” - David Autor, Professor of Economics, Massachusetts Institute of Technology
  • “…challenges misconceptions that distort our economic debates.” - Arthur Brooks, President of the American Enterprise Institute
  • “…serious thinking for serious thinkers. …a thought-provoking blueprint for growing middle- and working-class incomes.” - Mitt Romney, former Governor of Massachusetts
  • “Unintended Consequences should be read by anyone who takes for granted the superiority of progressive taxation and has not thought carefully about the trade-offs involved.” - The New Republic
  • “Unintended Consequences offers deep and well-argued analyses on almost every issue.” - The New York Times
  • “There are an amazing number of good ideas and interesting points made in Unintended Consequences. The thinking underlying it, and the obvious depth of understanding of the author, are very impressive.” - Steven Levitt, coauthor of Freakonomics; 2004 John Bates Clark Medal
  • “…a comprehensive explanation of the modern economy.” - Julian Robertson, Founder, Tiger Management
Upside of Inequality Oxford Unintended Consequences
Buy the Books
  • Macro Roundup
  • About Roundup
  • About Ed Conard
  • Highlights
  • Topics
  • Subscribe
Edward Conard
  • twitter
  • facebook
  • linkedin
  • youtube
  • Email
  • Text Message (SMS)
  • Twitter/X
  • LinkedIn
  • Facebook
  • WhatsApp Message
Subscribe to Macro Roundup Emails
  • Mentions 338
  • Primary focus 94
Showing 94 database articles primarily about Unemployment/Participation
Currently filtering by:
  • Remove Unemployment/Participation
  • Remove "primary topics only" restriction
  • Remove 'Database'
Show all 7,196 articles
For whatever topics you select (currently: Unemployment/Participation):
Choose search scope

Your importance filter 'Database' shows fewer articles.

Remove filters to see full article counts

“The Great Retirement Boom”: The Pandemic-Era Surge in Retirements and Implications for Future Labor Force Participation

Joshua Montes, Christopher Smith and Juliana Dajon Federal Reserve Board
Date Posted:
December 9, 2022
Is Database:
Database

In October 2022, the retired share of the American population was 1½ percentage points above its pre-pandemic trend. These 3.5 million workers account for essentially all of the shortfall in labor force participation rates. @federalreserve

Despite some improvement in the labor force participation rate for the working-age population since the early stages of the pandemic, the LFPR in October 2022 remained nearly 1½ percentage points below its pre-pandemic, February 2020 level (after making adjustments for changes in population weights introduced from the 2020 Census). The importance of retirements in accounting for this shortfall is illustrated in Figure 1, which shows the percentage of the working-age population that is not in the labor force for different reasons (black line) relative to February 2020, based on responses to the Current Population Survey. While earlier in the pandemic, factors other than retirements were an important contributor to elevated non-participation (such as non-participation while caregiving, the orange line), the percent of the population that was not in the labor force and retired (the[MRH1]  “retired share”) has steadily increased and in October 2022 was almost 1½ percentage points above its pre-pandemic level, representing an increase of more than 3½ million retirees and accounting for essentially all of the total shortfall in the LFPR.

In October 2022, the retired share of the American population was 1½ percentage points above its pre-pandemic trend. These 3.5 million workers account for essentially all of the shortfall in labor force participation rates., “…Despite some improvement in the labor force participation rate for the working-age population since the early stages of the pandemic, the LFPR in October 2022 remained nearly 1½ percentage points below its pre-pandemic, February 2020 level (after making adjustments for changes in population weights introduced from the 2020 Census). The importance of retirements in accounting for this shortfall is illustrated in Figure 1, which shows the percentage of the working-age population that is not in the labor force for different reasons (black line) relative to February 2020, based on responses to the Current Population Survey. While earlier in the pandemic, factors other than retirements were an important contributor to elevated non-participation (such as non-participation while caregiving, the orange line), the percent of the population that was not in the labor force and retired (the “retired share”) has steadily increased and in October 2022 was almost 1½ percentage points above its pre-pandemic level, representing an increase of more than 3½ million retirees and accounting for essentially all of the total shortfall in the LFPR….”

The Evidence The pre-pandemic trend, “…Even in the absence of the pandemic, the retired share would likely have risen, albeit more gradually, due to shifts in the age distribution of the population toward ages traditionally associated with higher retired shares (primarily, the movement of the Baby Boomer cohort into older ages). As one illustration of the importance of population aging, Figure 2 plots the retired share (solid line) alongside a counterfactual trend (dashed line)….”

“…. This trend is an estimate of how the retired share would have evolved in the absence of the pandemic and is derived by assuming the continuation of pre-pandemic, age-specific trends in retired shares, assuming the state of the business cycle remained similar to pre-pandemic levels, and accounting for the actual changes in the age distribution over this period (in section III, we discuss in more detail the calculation of this and other counterfactual retired shares). Over the five years prior to the pandemic, the retired share increased about 0.2 percentage point per year, and plausibly would have continued increasing at a similar pace in the absence of the pandemic. As of October 2022, the retired share remained 0.6 percentage point above the pre-pandemic expected trend, or about 1.6 million people (Figure 2). This gap between the actual and expected lines is an estimate of “excess retirements,” and the excess retirements gap remains sizeable. In fact, the retired share was slightly below trend just prior to the pandemic (about 0.2 percentage point), implying that excess retirements as a share of the population have increased by about 0.8 percentage point since February 2020, or about 2.1 million people. That increase in excess retirements explains a little more than half of the 1.4 percentage point increase the total retired share since February 2020, whereas the increasing expected retired share explains the rest (see Figure 3)….”
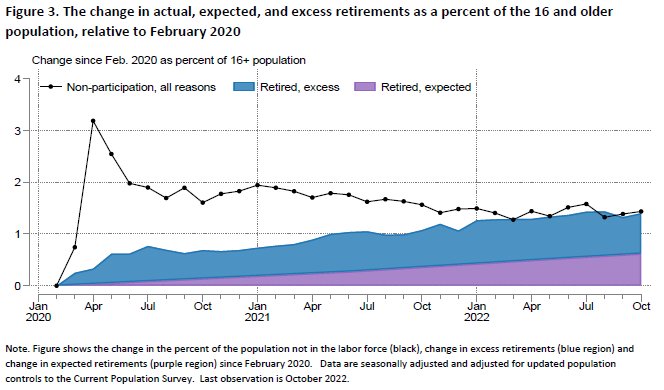
“…Thus, less than half of the increase in the retired share to date would likely have occurred even in the absence of the pandemic, suggesting that more than half of the current LFPR shortfall is a direct result of the pandemic on retirement….First, as discussed above, more than half of the increase in the retired share relative to February 2020 is due to an increase that would have been expected in the absence of the pandemic. Second, about two-thirds of the total increase in the excess retired share is attributable to those who were age 65 and older at the start of the pandemic, with a particularly sharp increase in excess retirements among those age 70 and older. The remaining one-third of the increase in the excess retired share is attributable to those age 55 to 64 when the pandemic began. Third, there is also substantial heterogeneity across education, race, and ethnic groups, with retired shares for those age 65 and older increasing more than expected for Whites relative to Blacks and Hispanics, and for those with a college education relative to those without….…Because the retired share has remained significantly elevated since increasing substantially at the start of the pandemic and has shown little sign of converging towards its ex-pandemic counterfactual, it may take some years for retirement behavior to normalize relative to pre-pandemic norms and for the retired share of the population to converge toward what it would be in the absence of pandemic-related influences. We view it as unlikely, however, that the retired share will fall substantially towards its pre-pandemic trend and that those who retired early will return to the labor force in large numbers, since most of the excess retirements are concentrated among people who are 65 and older who (given their age) would likely be retiring in greater numbers anyway over the next few years. That assessment is supported by the stabilization of the unretirement rate at its pre-pandemic level, well below the level it would need to reach for the retired share to fall substantially…”

Joshua Montes, Christopher Smith, and Juliana Dajon, ” “The Great Retirement Boom”: The Pandemic-Era Surge in Retirements and Implications for Future Labor Force Participation,” Federal Reserve Board, November 2022, https://www.federalreserve.gov/econres/feds/the-great-retirement-boom.htm

Brandon Adams Comment: “This is a great paper. I think the labor force participation rate could converge toward its pre-pandemic trend line faster than envisioned in this paper. The paper ignores asset markets altogether, and it seems clear to me that rapidly inflating retirement accounts in 2021 was a big part of this story. Towards the tail end of the time period covered in this paper, retirees met the unwelcome duo of rapidly decreasing asset prices and rapidly increasing consumer prices. This might or might not bring people in their 60s or 70s out of retirement, but it will almost surely slow the exit rate of those aged 40-60, and it might also bring back into the labor force some people in that age range who are currently sitting out.”

  • Unemployment/Participation
  • Workforce
Previous articleDecember 9, 2022All Pain and No Gain From Higher Interest Rates.@JosephEStiglitz argues that current inflationary pressure is supply-side driven and states higher interest rates may exacerbate inflationary pressures.Next articleDecember 9, 2022How Republicans Lost Their House Edge in MidtermsA change in the way votes are distributed has eroded a GOP edge in the House of Representatives that the party has enjoyed over the past decade. @foxjust @bloomberg
Showing 93 database articles primarily about Unemployment/Participation

What’s Behind the Declining Trend Unemployment Rate?

AI Summary. The structural unemployment rate fell from 7.8% to 4.8% between 1976 and 2024, with over half of the 3.3 percentage point decline driven by workforce composition shifts, particularly rising educational attainment, which alone accounts for 1 percentage point of the reduction.

Andreas Hornstein, Marianna Kudlyak, Greeshma Avaradi and Taerin Kim Federal Reserve Bank of San Francisco
Date Posted:
August 26, 2026
Is Database:
Database

Hornstein et al find that about half of the ~3pp drop in the trend unemployment rate since 1976 is due to compositional change in the work force towards lower unemployment “types ” – in particular, older and more educated workers.

Is rising education driving down structural unemployment?

Core argument: The U.S. trend unemployment rate fell 3.3 percentage points—from 7.8% in 1976 to 4.8% in 2024—with rising educational attainment alone accounting for 1.0 percentage point of that structural decline.

We find that the trend unemployment rate declined from 7.8% in 1976 to 4.8% in 2024 [Figure 1]. Roughly half of that decline reflects compositional change. Figure 2 separates the estimated cumulative change in the annual unemployment trend since 1976 into its components. The total decline was about 3.3 percentage points by 2024. Changes in workforce composition account for a little more than half of that decline. Rising educational attainment is the single largest compositional force, lowering the trend about 1pp. Figure 4 plots estimated education shares for entering cohorts of women, and these patterns are similar for male cohorts (not shown). The figure shows a steady long-run fall in the share of new female cohorts with less than high school education and a steady rise in the share with some college or a college degree. [Returning to Figure 2], changes in group-specific LFP rate trends contribute only ~0.3 pp. The remaining decline, a bit under 1pp, comes from lower group-specific trend unemployment.

Takeaways by Macro Roundup® AI

  1. The U.S. trend unemployment rate fell 3.3 percentage points—from 7.8% in 1976 to 4.8% in 2024—with rising educational attainment alone accounting for 1.0 percentage point of that structural decline.
  2. Workforce compositional shifts explain slightly more than half of the 3.3-percentage-point decline in trend unemployment since 1976, making demographic change the dominant driver over the period.
  3. Group-specific labor force participation trends contributed only 0.3 percentage points to the trend unemployment decline, while lower group-specific unemployment rates drove the remaining approximately 1.0 percentage point reduction.

Related Articles:

  • Global Views: They’re Not Hiking — The decline in unemployment has been driven by lower labor force participation, not an increase in employment. Hatzius stresses continued weakness in wage…
  • Labor Force Participation Is High If You Measure It Right — The overall labor force participation rate is a misleading measure of labor market health because it does not account for age-related variation in work patterns, making it especially distorted when large population groups shift into retirement-age brackets.
  • Unemployment/Participation
  • Workforce

College Grads Struggle to Find Jobs. Non-Grads Are Giving Up

AI Summary. The narrowing unemployment gap between young college graduates and non-graduates reflects rising labor force dropout among non-graduates, not equal job market outcomes; the share of young non-graduates who are employed is 1.7 percentage points below pre-pandemic levels and falling, while graduates are near recovery.

Justin Fox Bloomberg
Date Posted:
August 25, 2026
Is Database:
Database

Labor force participation is rising for American college graduates aged 25–29, and is now at 89.4% – above its pre-pandemic level. Participation among non-college members of that age cohort is falling; at 78.7%, it is now below its pre-pandemic level.

Are non-graduates disappearing from the job market?

Core argument: The narrowing education-unemployment gap among young adults reflects labor force withdrawal by non-degree holders—not diminished diploma value—as workers who stop seeking jobs are excluded from unemployment calculations.

The narrowing of [the unemployment gap btw college and non-college workers] in recent years has lent support to narratives that college diplomas are losing their value amid the rise of large language models, the purported return of blue-collar work, and other job market changes. But while it may well be that diplomas have lost value, the recent shrinking of the young-adult education-unemployment gap seems to be driven mainly by a different phenomenon. Growing numbers of young adults without college degrees simply aren’t trying to find work and thus aren’t counted in unemployment calculations. The employment-population ratio for young college grads is not far off from where it was just before the pandemic and seems as if it might be headed upward again after a sharp drop in 2023 and 2024, for non-grads it is 1.7 percentage points lower than before the pandemic and clearly trending downward.

Takeaways by Macro Roundup® AI

  1. The narrowing education-unemployment gap among young adults reflects labor force withdrawal by non-degree holders—not diminished diploma value—as workers who stop seeking jobs are excluded from unemployment calculations.
  2. Young adults without college degrees carry an employment-population ratio 1.7 percentage points below pre-pandemic levels and trending downward, while college graduates have nearly recovered to pre-pandemic parity.

Related Articles:

  • Labor Force Participation Is High If You Measure It Right — The overall labor force participation rate is a misleading measure of labor market health because it does not account for age-related variation in work patterns, making it especially distorted when large population groups shift into retirement-age brackets.
  • How Labor Force Participation Has Diverged Across Genders — Male labor force participation has fallen steadily since the 1970s, while female participation rose sharply before plateauing, driven by shifts in education levels and age composition rather than a single cause.
  • AI, Immigration, and Collapsing Labor Force Participation — Declining labor force participation concentrates economic output among fewer workers, raising the return on automation and making productivity growth the primary driver of expansion. Any productivity shortfall carries greater consequences because a shrinking worker base cannot compensate through increased participation.
  • Unemployment/Participation
  • Politics
  • Workforce
    • Education
      • College
      • K-12
    • Family/Marriage

The Big Exceptions To The American Manufacturing Jobs Decline

AI Summary. U.S. aerospace and electrical components manufacturing are the two largest sources of job growth in an otherwise declining manufacturing sector, driven by record airline order backlogs and surging demand for electrical infrastructure from data centers. Dedicated data center consumption of electrical equipment and components more than doubled between 2019 and

Jiaxin (Jason) He Agglomerations
Date Posted:
July 24, 2026
Is Database:
Database

The US has lost 300,000 manufacturing jobs since their recent peak in Q2 2023. Two subsectors have seen strong job growth: aerospace manufacturing added 43,000 jobs, and electrical equipment, cable and battery manufacturing added 36,200.

Are aerospace and electrical components bucking the broader manufacturing decline?

Core argument: Aerospace posted a $116.7 billion trade surplus—the largest of any U.S. manufacturing industry—while leading all sectors in job growth since 2023, driven by record commercial airline order backlogs and Boeing's return to profitability and high delivery volumes.

Aerospace leads all manufacturing industries in job growth since 2023. Last year it also posted the largest nominal trade surplus of any manufacturing industry, at $116.7 billion. Driving the growth has been strong commercial and passenger airline demand, including a record-high order backlog. Boeing, the world’s leading airplane manufacturer, returned to profitability and high delivery volumes in 2025. The employment surge in the electrical components subsector tells a different story. It owes its strength to two industries: electrical equipment manufacturing and batteries, wires, cables, and miscellaneous electrical components. These are among the industries that bore the brunt of the China Shock and suffered acute decline in the 2000s. Green energy and electric vehicles likely contributed to their initial recovery, raising demand for batteries and electrical infrastructure. But their continued growth even after the cancellation of EV subsidies in 2025 points to a different, potent, and entirely unsurprising driver: Artificial Intelligence. AI’s manufacturing footprint runs the length of the supply chain. Dedicated data centers more than doubled their real consumption of electrical equipment and components from 2019 to 2024.

Takeaways by Macro Roundup® AI

  1. Aerospace posted a $116.7 billion trade surplus—the largest of any U.S. manufacturing industry—while leading all sectors in job growth since 2023, driven by record commercial airline order backlogs and Boeing's return to profitability and high delivery volumes.

Related Articles:

  • Does the Import Invasion Explain the Mysterious Disappearance of Productivity Growth in U.S. Manufacturing? — Rising import penetration in U.S. manufacturing after 2000 is strongly linked to slower productivity growth, as foreign competition reduced domestic sales, investment, and innovation capacity, with offshoring of production to Asia severing the link between design and process improvement.
  • Midyear Outlook — AI investment is crowding out rival capital projects by absorbing scarce physical inputs—grid capacity, construction labor, metals, and engineering talent—while semiconductor prices surge where supply constraints meet surging demand. With hyperscaler free cash flow exhausted, over 80% of future AI capital spending requires external financing, including fresh equity issuance.
  • What Would It Take to Bring Back US Manufacturing? Part 1: America’s Structural Headwinds — Bridgewater estimates that closing the ~$3T gap btw US manufacturing output and goods consumption will be an uphill battle. Largely due to manufacturing wages…
  • Unemployment/Participation
  • Productivity
    • Investment
  • Workforce

The Labor Market Explains Why Inflation Won’t Go Away

AI Summary. A labor market operating below the unemployment level consistent with stable prices for an unusually long stretch sustains upward pressure on wages and prices, keeping inflation persistently elevated. Reducing inflation toward the 2% target requires maintaining higher interest rates until excess labor demand is eliminated.

Torsten Sløk Apollo
Date Posted:
July 17, 2026
Is Database:
Database

US unemployment has been under the Fed’s 4.5% estimate of the non-accelerating inflation rate of unemployment (NAIRU) for 57 months. Sløk argues “persistent tightness is a key reason inflation has remained elevated.”

Does tight labor demand explain persistent inflation pressure?

With the Fed estimating the non-accelerating inflation rate of unemployment (NAIRU) at below 4.5%, and unemployment having stayed at or below that level for 57 months, tied for the longest such streak on record, the labor market has been operating in excess-demand territory for an unusually long time. That persistent tightness is a key reason inflation has remained elevated: when unemployment runs below NAIRU, wages and prices face sustained upward pressure. Prior episodes of sub-4.5% unemployment were typically far shorter. The current one is one of the longest on record, which helps explain why the ongoing inflation overshoot since 2021 has been so stubborn. The bottom line is that a strong economy is the reason why inflation has been high, and only by keeping rates higher for longer can the Fed cool inflation down towards the FOMC’s 2% inflation target.

Related Articles:

  • The U.S. Job Market is (Still) Inflationary — Notwithstanding the soaring prices of components for manufacturing, Klein argues that “the most important thing to understand about US inflation is that the…
  • Labor Force Participation Is High If You Measure It Right — The overall labor force participation rate is a misleading measure of labor market health because it does not account for age-related variation in work patterns, making it especially distorted when large population groups shift into retirement-age brackets.
  • Baby Busts and Growth Booms: Demographic Change and the Macroeconomy — Cross-country evidence from 1950 to 2020 shows that a 1pp lower birth rate is associated with 22 log points (~25%) higher GDP per worker 40 years later and 29…
  • Unemployment/Participation
  • GDP
    • Inflation
  • Monetary Policy
  • Workforce

Labor Force Participation Is High If You Measure It Right

AI Summary. The overall labor force participation rate is a misleading measure of labor market health because it does not account for age-related variation in work patterns, making it especially distorted when large population groups shift into retirement-age brackets.

Justin Fox Bloomberg
Date Posted:
July 16, 2026
Is Database:
Database
Is Important:
Important

Adjusted for the age composition of the population, US labor force participation, at 61.8%, is near an all-time high, reflecting delayed retirement of older workers.

Does labor force participation tell us what we think it does?

The labor force participation rate is the number of people 16 and older who have jobs or are actively looking for them, divided by the civilian (that is, not uniformed military) noninstitutional (that is, not in prison or the like) population 16 and older. While this percentage can tell us useful things about, say, the sustainability of Social Security or the overall availability of labor, its validity as a gauge of the health of the labor market is limited by the reality that labor force participation varies greatly by age. It’s a flawed metric that is currently more flawed than usual as the youngest members of the giant baby boom generation age into their mid-60s. The addition this year of nearly 1.7 million 65-and-older Americans to the BLS population estimates, because of belated adjustments stemming from the 2020 Census, just adds to the distortions.

Related Articles:

  • Baby Busts and Growth Booms: Demographic Change and the Macroeconomy — Cross-country evidence from 1950 to 2020 shows that a 1pp lower birth rate is associated with 22 log points (~25%) higher GDP per worker 40 years later and 29…
  • AI, Immigration, and Collapsing Labor Force Participation — Declining labor force participation concentrates economic output among fewer workers, raising the return on automation and making productivity growth the primary driver of expansion. Any productivity shortfall carries greater consequences because a shrinking worker base cannot compensate through increased participation.
  • How Labor Force Participation Has Diverged Across Genders — Male labor force participation has fallen steadily since the 1970s, while female participation rose sharply before plateauing, driven by shifts in education levels and age composition rather than a single cause.
  • Unemployment/Participation
  • Workforce

'Nobody Wants to Work Anymore': Lifetime Labor Market Experiences and the Decline of Male LFP in the United States

AI Summary. Declining male labor force participation in the United States is driven by cohort-level beliefs shaped by lifetime exposure to weak male labor markets, with each generation participating less than the last at every age.

Remy Levin and Daniela Vidart National Bureau of Economic Research
Date Posted:
June 16, 2026
Is Database:
Database
Is Important:
Important

Btw 1986 and 2019, prime-age males who grew up observing a one–SD lower male earnings history had a 7pp lower LFP rate in adulthood, holding current labor‑market conditions fixed.

Does weak labor market exposure permanently reduce male workforce participation?

Core argument: Male labor force participation decline correlates strongly with cohort-level lifetime labor market experiences, driving persistent participation gaps across generations independent.

We propose a new channel contributing to the long-run decline in [male labor force participation] (MLFP) in the United States: changes in American men’s lifetime experiences of the aggregate male labor market have shaped their beliefs about the returns to participation, influencing labor supply decisions in ways that persist even in the face of current market conditions. MLFP and national lifetime male labor market experiences, holding contemporaneous conditions fixed, are highly correlated over time (Figure 1, Panel A). Second, the decline in MLFP is largely driven by cohort-level differences: recent cohorts participate at lower rates than previous generations at every age (Figure 1, Panel B). These patterns suggest that men’s labor market participation is the history, embedded in each cohort’s memory, of the labor markets experienced by the men around them. The effects on MLFP are stronger for experiences of same-race male labor markets, demonstrating the central role of reference-group identity, and are driven by conditions experienced during men’s formative childhood years not explained by educational attainment of subjects or their fathers. Finally, we show that lifetime male labor market experiences are correlated with direct measures of men’s personal wage and employment expectations, but not their expectations for the macroeconomy as a whole.

Takeaways by Macro Roundup® AI

  1. Male labor force participation decline correlates strongly with cohort-level lifetime labor market experiences, driving persistent participation gaps across generations independent.
  2. Same-race male labor market conditions experienced during childhood shape adult participation expectations more than macroeconomic beliefs, leading to reference-group-driven labor.
  3. Recent cohorts participate at lower rates than previous generations at every age, demonstrating that formative-year labor market exposure—not education—drives long-run.

Related Articles:

  • How Labor Force Participation Has Diverged Across Genders — Male labor force participation has fallen steadily since the 1970s, while female participation rose sharply before plateauing, driven by shifts in education levels and age composition rather than a single cause.
  • Bachelors Without Bachelor’s: Gender Gaps in Education and Declining Marriage Rates — The rise in female college enrollment from 1930-80 hasn’t reduced marriage rates for college women. “The overall decline in marriage rates is driven almost…
  • Post-Pandemic Recovery for America’s Prime Age Labor Force: A Tale of Two Sexes — Nicholas Eberstadt notes that the labor force participation rate for prime-age women is up 5pp since the pandemic to an all-time high, while the rate for…
  • Unemployment/Participation
  • Workforce
    • Demographics
© Copyright 2026 Coherent Research Institute · All Rights Reserved · Privacy · Terms