Edward Conard

Top Ten New York Times Bestselling Author

  • “…serious thinking for serious thinkers. …a thought-provoking blueprint for growing middle- and working-class incomes.” - Mitt Romney, former Governor of Massachusetts
  • “Unintended Consequences is full of substance, it is one of the must-read books of the year, and once I finish it I will be giving it a second read through right away.” - Tyler Cowen, Professor, George Mason University
  • “…a very valuable contribution.” - Larry Summers, former Secretary of the Treasury and director of the National Economic Council, president emeritus, Harvard University
  • “…reminds us that inequality sends a signal of what society lacks most, in America’s case, entrepreneurship and risk taking.” - Lawrence Lindsey, CEO, The Lindsey Group, former Director of the National Economic Council
  • “Unintended Consequences is far smarter and more thought-provoking than most economics written for the general public” - Greg Mankiw, Harvard University, Former Chairman of the Council of Economic Advisors
  • “Unintended Consequences represents the most cogent and persuasive analysis of the Financial Crisis to date.” - Andrei Shleifer, 1999 John Bates Clark Medal Winner
  • “…a comprehensive explanation of the modern economy.” - Julian Robertson, Founder, Tiger Management
  • “…a must-read for serious students of economic policy.” - Glenn Hubbard, Dean, Columbia Business School, and former Chairman of the Council of Economic Advisers
  • “…serious thinking for serious thinkers. …a thought-provoking blueprint for growing middle- and working-class incomes.” - Mitt Romney, former Governor of Massachusetts
  • “…challenges misconceptions that distort our economic debates.” - Arthur Brooks, President of the American Enterprise Institute
  • “A full-throated defense of economic dynamism.” - The Wall Street Journal
  • “…reminds us that inequality sends a signal of what society lacks most, in America’s case, entrepreneurship and risk taking.” - Lawrence Lindsey, CEO, The Lindsey Group, former Director of the National Economic Council
Upside of Inequality Oxford Unintended Consequences
Buy the Books
  • Macro Roundup
  • About Roundup
  • About Ed Conard
  • Highlights
  • Topics
  • Subscribe
Edward Conard
  • twitter
  • facebook
  • linkedin
  • youtube

Macro Roundup

  • Email
  • Text Message (SMS)
  • Twitter/X
  • LinkedIn
  • Facebook
  • WhatsApp Message
Subscribe to Macro Roundup Emails
Select topics to choose: articles that mention them (broader) or articles mainly about them (focused)
  • Mentions 0
  • Primary focus 0
Showing all 7,294 Macro Roundup articles
When you search for any topic (like GDP, Inflation, or Banking), choose:
Choose search scope

Thursday, August 3, 2023

The Rasputin Effect: Global Resilience To Higher Rates

AI Summary. The US corporate sector's financial balance remains in surplus, a condition that has never preceded a recession, and central banks have withdrawn only about one third of the $11tn in global liquidity they created. Excess US household savings are projected to run out in the following year, pointing to modestly weaker conditions rather than a significant contraction.

Michael Cembalest J.P. Morgan
Date Posted:
August 3, 2023

Michael Cembalest notes that, “There’s still plenty of liquidity in the system,” as central banks have removed only 1/3 of the $11 trillion in liquidity created during the pandemic period.

Why has the global economy withstood higher interest rates?

Core argument: The US corporate sector financial balance remains in surplus, a condition that has never preceded a recession, unlike the yield curve's recession signal.

While a simple read of the yield curve points to recession, the health of the US corporate sector does not: the corporate sector financial balance is still in surplus, a condition which has never preceded a recession. Central banks have only removed around one third of the $11 trillion in global liquidity they created in 2020/2021. There’s still plenty of liquidity in the system and the cost of money is not prohibitive. Excess US household savings are projected to run out sometime in 2024, and while current economic indicators are robust, there’s weakness in Conference Board leading indicators. The overall pulse does not point to a significant contraction, just to modestly weaker US conditions in 6-9 months.

Takeaways by Macro Roundup® AI

  1. The US corporate sector financial balance remains in surplus, a condition that has never preceded a recession, unlike the yield curve's recession signal.
  2. Central banks have withdrawn only about one third of the $11 trillion in global liquidity created in 2020–2021, leaving ample liquidity and a cost of money that is not prohibitive.
  3. Excess US household savings are projected to run out sometime in 2024, and with weakness in Conference Board leading indicators, the overall pulse points to modestly weaker US conditions in 6–9 months rather than significant contraction.

Related Articles:

  • Most Global Economies Remain in Disequilibrium, Requiring Policy Action — An investment framework holds that markets and economies are driven by three equilibriums — spending in line with output and capacity, incomes in line with debts, and normal risk premiums across assets — interacting with two policy levers, monetary and fiscal policy. When these conditions are absent, the resulting social, political, and business strains produce changes until equilibrium is restored.
  • Financial Markets
  • GDP
    • Business Cycle
    • Growth

There Is No "Stealth Fiscal Stimulus"

AI Summary. The U.S. federal budget deficit has widened by about 3-4 percentage points of GDP, with lower revenues mostly attributable to a plunge in capital gains tax receipts after an earlier windfall and to the collapse in Federal Reserve payments to the Treasury. Higher outlays are almost entirely attributable to surging interest payments on Treasury debt.

Matt Klein The Overshoot
Date Posted:
August 3, 2023

The increase in the US federal deficit has been driven by higher net interest costs, lower remittances to the Treasury from the Federal Reserve, and lower capital gain income. @M_C_Klein

Is the wider federal deficit a hidden fiscal stimulus?

Core argument: The U.S. federal budget deficit has widened by roughly 3–4pp of GDP since the start of 2022, a shift attributed to falling revenues and rising interest costs rather than stealth fiscal stimulus.

The U.S. federal budget deficit has widened by about 3-4pp of GDP since the start of 2022. The downturn in revenues is mostly attributable to the plunge in capital gains tax receipts after the windfall of 2021/2022, as well as the collapse in dividends paid by the Federal Reserve to the Treasury. Meanwhile, the increase in outlays is almost entirely attributable to the surge in interest payments on Treasury debt.

Takeaways by Macro Roundup® AI

  1. The U.S. federal budget deficit has widened by roughly 3–4pp of GDP since the start of 2022, a shift attributed to falling revenues and rising interest costs rather than stealth fiscal stimulus.
  2. The revenue decline stems mostly from the plunge in capital gains tax receipts after the 2021/2022 windfall, together with the collapse in dividends the Federal Reserve pays to the Treasury.
  3. The increase in federal outlays since the start of 2022 is almost entirely attributable to the surge in interest payments on Treasury debt.

Related Articles:

  • Net Interest Payments On External US Debt — The US holds net external debt of about 50% of its GDP but earns roughly 4% on its foreign lending while paying about 3% on its borrowing, leaving an implied net interest rate of 2.4%. This slows, without eliminating, the balance-of-payments adjustment to higher interest rates as net interest payments rise further.
  • The Budget and Economic Outlook: 2023 to 2033 — The Congressional Budget Office projects the federal deficit rising to 6.9% of GDP in 2033, well above the 3.6% average of the past 50 years, with net interest costs a major contributor. Federal debt held by the public is projected to climb from 98% of GDP to 118% by 2033 and 195% by 2053.
  • Business Cycle
  • Fiscal Policy
    • Fiscal Deficits
  • GDP
    • Growth

Fitch Is Right

AI Summary. Inflation functions as a partial default: cumulative inflation above the 2% target means US debt is repaid in dollars worth 12.4% less, economically equivalent to a 12.4% haircut for creditors. The author argues that borrowing and printing $5tn without a repayment plan makes future inflationary episodes more likely and reduces global appetite for US debt.

John Cochrane The Grumpy Economist
Date Posted:
August 3, 2023

.@JohnHCochrane argues that Fitch was right to downgrade the US as inflation is effectively a default. “If you only repaid 87.6% of your mortgage, you can be sure the bank would see you as a worse credit risk going forward.”

Is inflation above target economically equivalent to a partial default?

Core argument: Cumulative US inflation above the 2% target means outstanding debt is repaid in dollars worth 12.4% less than if inflation had been 2%, economically equivalent to a 12.4% haircut.

Inflation is the economic equivalent of a partial default. The debt was sold under a 2% inflation target, and people expected that or less inflation. The government borrowed and printed $5 Trillion with no plan to pay it back, devaluing the outstanding debt as a result. Cumulative inflation so far means debt is repaid in dollars that are worth 12.4% less than if inflation had been 2%. That's economically the same as a 12.4% haircut. If you only repaid 87.6% of your mortgage, you can be sure the bank would see you as a worse credit risk going forward. The probability that the US inflates again, that in the next crisis they do the same thing, is unquestionably larger. The world's appetite for boundless amounts of US debt is unquestionably smaller.

Takeaways by Macro Roundup® AI

  1. Cumulative US inflation above the 2% target means outstanding debt is repaid in dollars worth 12.4% less than if inflation had been 2%, economically equivalent to a 12.4% haircut.
  2. The US government borrowed and printed $5 trillion with no plan to pay it back, devaluing debt that had been sold under a 2% inflation target.
  3. The probability that the US inflates again in the next crisis is larger, and the world's appetite for boundless amounts of US debt is smaller.

Related Articles:

  • What We’ve Learned About Inflation — Fiscal theory holds that a one-time $5tn fiscal expansion produces a one-time rise in the price level sufficient to inflate away $5tn of debt value, after which inflation stops even if the Federal Reserve does nothing. Raising interest rates lowers current inflation at the cost of more-persistent inflation, a beneficial smoothing.
  • Inflation
  • Fiscal Policy
    • Fiscal Deficits
  • GDP

Birth, Death, and Wealth Creation

AI Summary. The median age at which US companies went public rose from 7.9 years in 1976–2000 to 9.5 years in 2001–2022, implying that more wealth creation now occurs in private markets. Research on more than 28,000 US-listed companies since 1926 finds that just under 60% destroyed $9.1tn of wealth while about 2% created $50tn.

Michael Mauboussin and Dan Callahan Morgan Stanley
Date Posted:
August 3, 2023
Is Database:
Database

As firms have stayed private longer wealth creation has shifted from public to private markets. @mjmauboussin

Are companies staying private longer shifting wealth creation away from public markets?

Core argument: Hendrik Bessembinder finds that of more than 28,000 U.S.-listed companies from 1926 to 2022, just under 60% destroyed $9.1 trillion of wealth while about 40% created $64.2 trillion, for a net $55.1 trillion.

The median age at IPO was 7.9 years from 1976 to 2000 and rose to 9.5 years from 2001 to 2022. One implication of companies staying private longer is that wealth creation has shifted to private markets from the public markets. To illustrate the point, Amazon’s market capitalization was $749 million when it went public in 1997 and $1.3 trillion as of June 30, 2023 (in 2022 dollars). The company was three years old when it did its IPO. Essentially all of its wealth creation occurred when it was public. Hendrik Bessembinder, a professor of finance, has measured the wealth creation of more than 28,000 U.S.listed companies since 1926. A company creates wealth if it generates returns in excess of one-month Treasury bill rates. He found that from 1926 to 2022, just under 60% of them destroyed $9.1 trillion and the other 40% or so created $64.2 trillion. Just 2% of the sample created $50 trillion of the net total of $55.1 trillion, and the top 3 firms (Apple, Microsoft, and ExxonMobil) created almost $6 trillion.

Takeaways by Macro Roundup® AI

  1. Hendrik Bessembinder finds that of more than 28,000 U.S.-listed companies from 1926 to 2022, just under 60% destroyed $9.1 trillion of wealth while about 40% created $64.2 trillion, for a net $55.1 trillion.
  2. Just 2% of Bessembinder's sample created $50 trillion of the $55.1 trillion net total, with Apple, Microsoft, and ExxonMobil accounting for almost $6 trillion.
  3. The median age at IPO rose from 7.9 years over 1976–2000 to 9.5 years over 2001–2022, one implication being that wealth creation has shifted from public to private markets.

Related Articles:

  • Mr. Toad’s Wild Ride: The Impact Of Underperforming 2020 and 2021 US IPOs — Between 40% and 60% of US initial public offerings generate negative returns even in favorable periods, so average IPO returns far exceed median returns and depend on a small set of large winners. Excluding just the top 3% of IPOs turns average net returns negative and cuts average absolute returns by more than half.
  • The Economics of Inequality in High-Wage Economies — United States Income, Wealth, Consumption, and Inequality Diana Furchtgott-Roth
  • Financial Markets
  • GDP

The Ultra-Rich Are Flourishing and Sticking Around In California

AI Summary. California is home to 113 billionaires, more than any country except China, and added over 116,000 millionaire taxpayers between the end of 2019 and 2021, according to the state's Department of Finance. The number of residents reporting income above $50m rose 158% to 3,182.

Eliyahu Kamisher and Biz Carson Bloomberg
Date Posted:
August 3, 2023

Despite net migration from California between 2019 and 2021, California added more than 116,000 millionaire taxpayers. The top 1% of earners account for roughly 50% of personal income tax revenue.

Is California's population of ultra-wealthy residents growing?

Core argument: California added more than 116,000 millionaire taxpayers from the end of 2019 through 2021, according to the state's Department of Finance, far outpacing any loss of high-net-worth taxpayers during the pandemic.

California has more billionaires — 113 — than in any country except China. The ranks of mere millionaires have grown as well, far outpacing any loss of high-net-worth taxpayers during the pandemic. From the end of 2019 through 2021, California added more than 116,000 millionaire taxpayers, according to the state’s Department of Finance. The number of residents making more than $50 million surged 158% to 3,182. And that likely underestimates the riches. While the tax data reflects salaries along with income from stock and real estate sales, the ultra-wealthy often avoid income taxes by borrowing against their wealth instead of selling assets that would incur a tax burden. In total, more than 288,000 Californians, or 0.7% of residents, reported over $1 million in income in 2021.

Takeaways by Macro Roundup® AI

  1. California added more than 116,000 millionaire taxpayers from the end of 2019 through 2021, according to the state's Department of Finance, far outpacing any loss of high-net-worth taxpayers during the pandemic.
  2. The number of California residents making more than $50 million surged 158% to 3,182, while more than 288,000 Californians, or 0.7% of residents, reported over $1 million in income in 2021.
  3. California is home to 113 billionaires, more than any country except China, and the tax data likely understates that wealth because the ultra-wealthy often borrow against their wealth rather than sell assets that would incur a tax burden.

Related Articles:

  • The Population of California Declined, Again — California's population fell by 138,443 to 38.94 million, a third consecutive annual decline, according to state data. The main driver has been residents moving to other states such as Texas, Nevada, Idaho and Oregon, with net outmigration reaching a record 407,000 people and now spanning every education and income group.
  • Taxes, Revenues, and Net Migration In California — California's top income tax bracket shows the highest net out-migration rate, with departing high earners not replaced by other high earners at the same rate. Potential net outflows of taxable income reached nearly $4bn in the year federal tax reform took effect and $10.7bn around the COVID-19 pandemic.
  • Taxing Billionaires: Estate Taxes and the Geographical Location of the Ultra-Wealthy — The authors estimate that US billionaires move to states without estate taxes as they age, with $80.7bn of Forbes 400 wealth escaping estate taxation as a result. They find that for the average state the added estate tax revenue exceeds forgone income tax revenue by 31%, with California a notable exception.
  • Taxation
  • Fiscal Policy

The Rapid Loss Of Antarctic Sea Ice Brings Grim Scenarios Into View

AI Summary. Unusual wind and wave patterns are a leading short-term explanation for the loss of Antarctic sea ice, which holds the continent's coastal ice shelves in place. If those shelves collapsed, continental ice could flow rapidly into the oceans; the West Antarctic ice sheet alone holds enough water to raise global sea level by 11 feet.

Economist Staff The Economist
Date Posted:
August 3, 2023

After remaining relatively stable and actually growing between 1976 to 2014, Antarctic sea ice is at a record low, six standard deviations below the 1991-2020 levels.

How does shrinking Antarctic sea ice threaten global sea levels?

Core argument: The west Antarctic ice sheet alone contains enough water to raise global sea level by 11 feet, and a collapse of the coastal ice shelves would open the way for continental ice to flow rapidly into the oceans.

One of the leading short-term explanations is unusual patterns of wind and waves. Throughout June and July, gusts traveling from the Bellingshausen Sea towards the South Pole prevented ice from forming near the Antarctic Peninsula. Weather systems emanating from storms in the Indian Ocean—brought about by shifts in two regular atmospheric fluctuations, the El Niño Southern Oscillation and the Southern Annular Mode—may also have broken up sea ice as it began to form in East Antarctica. The ring of sea ice around Antarctica holds in place the continent’s coastal ice shelves, which in turn do the same for its glaciers and ice sheets. If those ice shelves were to collapse—as the Conger shelf in east Antarctica did in 2022—the gates would open for continental ice to flow rapidly into the oceans. The west Antarctic ice sheet alone contains enough water to increase global sea level by 11 feet.

Takeaways by Macro Roundup® AI

  1. The west Antarctic ice sheet alone contains enough water to raise global sea level by 11 feet, and a collapse of the coastal ice shelves would open the way for continental ice to flow rapidly into the oceans.
  2. Antarctica's ring of sea ice holds the continent's coastal ice shelves in place, which in turn restrain its glaciers and ice sheets; the Conger shelf in east Antarctica collapsed in 2022.
  3. Gusts traveling from the Bellingshausen Sea toward the South Pole through June and July prevented ice from forming near the Antarctic Peninsula, one of the leading short-term explanations for the loss of Antarctic sea ice.

Related Articles:

  • Antarctic Sea Ice Levels Dive In ‘Five-Sigma Event’, As Experts Flag Worsening Consequences For Planet — Sea ice around Antarctica has fallen to an all-time low, following earlier record lows, and for the first time in the observational record it has failed to substantially recover during winter, leaving vast stretches of coastline ice free. Scientists describe the decline as a five-sigma event.
  • Antarctic Sea Ice Has Shrunk By An Area Nine Times The Size Of Britain — Antarctic sea ice cover fell to 10.7m square km, 1.15m square km below the prior record low for that date and 2.3m square km below the 1981–2010 average. Scientists have not established why sea ice around the continent dropped so steeply after an earlier period of growth.
  • Science
    • Global Warming

What This Year’s ‘Astonishing’ Ocean Heat Means for the Planet

AI Summary. The planet's average sea surface temperature reached a record high and the ocean has stayed exceptionally warm, with North Atlantic readings running more than 2°F above typical levels and one buoy recording 101.1°F, possibly a world record. Scientists expect warm ocean conditions to continue as El Niño intensifies.

Elena Shao New York Times
Date Posted:
August 3, 2023

Last week a buoy off the coast of Florida recorded a reading of 101.1°F which might be a record for sea surface temperature.

How warm have ocean temperatures become this year?

Core argument: The planet's average sea surface temperature spiked to a record high in April and has remained exceptionally warm since, with the North Atlantic consistently running more than 2°F above typical levels for this time of year.

The planet’s average sea surface temperature spiked to a record high in April and the ocean has remained exceptionally warm ever since. The North Atlantic has seen some of the most exceptional warmth, with recent temperatures consistently reaching more than 2°F higher than what is typical for this time of year. Last week, one reading from a buoy recorded a stunning 101.1°F, possibly a world record for sea surface temperatures. The eruption of an underwater volcano in the Pacific Ocean near Tonga last year, which spewed tens of millions of tons of water vapor into the stratosphere, may have also influenced this year’s ocean temperatures. Water vapor, like carbon dioxide, is a greenhouse gas that traps heat near Earth’s surface. Scientists expect warm ocean conditions to continue into the fall, with El Niño intensifying in the months ahead.

Takeaways by Macro Roundup® AI

  1. The planet's average sea surface temperature spiked to a record high in April and has remained exceptionally warm since, with the North Atlantic consistently running more than 2°F above typical levels for this time of year.
  2. A buoy recorded a sea surface temperature of 101.1°F, possibly a world record.
  3. Scientists expect warm ocean conditions to persist into the fall with El Niño intensifying, and the eruption of an underwater volcano near Tonga, which spewed tens of millions of tons of heat-trapping water vapor into the stratosphere, may have influenced this year's ocean temperatures.

Related Articles:

  • Florida Ocean Temperatures At ‘Downright Shocking’ Levels — Much of Florida is recording its warmest year on record, with temperatures 3–5 degrees above normal and coastal waters in the Florida Keys reaching 92–96 degrees versus the more typical upper 80s. The National Oceanic and Atmospheric Administration reports about 40% of the world's oceans face a marine heat wave, the highest share on record.
  • Science
    • Global Warming

Friday, August 4, 2023

The Startup Surge Continues: Business Applications on Track for Second-Largest Annual Total on Record

AI Summary. Americans filed nearly 2.7m business applications in the first half of the year, up 5% from the prior year and 52% above the same period in 2019. One-third were applications with a high likelihood of hiring employees, 36% above the comparable 2019 total.

Daniel Newman Economic Innovation Group
Date Posted:
August 4, 2023
Is Database:
Database

Based on first-half new business formation, 2023 will be just shy of 2021’s record number of new firms likely to hire employees. @InnovateEconomy

Are Americans starting new businesses at rates well above prepandemic levels?

Core argument: One-third of the filings were "high propensity" applications under the Census Bureau's Business Formation Statistics, identifying businesses likely to hire employees if and when they become operational.

Early-stage business activity across the United States remains robust through the first half of 2023, as the pace of new business formation strengthened over last year. Individuals filed nearly 2.7 million applications to start a business between January and June of this year, a 5% increase over 2022 and a staggering 52% increase over the same period in 2019. One-third of those filings were for new businesses likely to hire employees—a key subset of applications from the Census Bureau’s Business Formation Statistics demonstrating a “high propensity” to hire staff, if and when the business becomes operational. The volume of likely employer applications also remained well above prepandemic levels, surpassing the total from the first six months of 2019 by 36%.

Takeaways by Macro Roundup® AI

  1. One-third of the filings were "high propensity" applications under the Census Bureau's Business Formation Statistics, identifying businesses likely to hire employees if and when they become operational.
  2. Likely employer applications in the first six months of 2023 exceeded the total from the same period in 2019 by 36%.

Related Articles:

  • Startup Surge Stood Firm Against Economic Headwinds in 2022 — Americans filed nearly 1.7m applications for new businesses classified by the U.S. Census Bureau as likely to hire employees, 27.8% above the pre-pandemic level and the second-highest total in the series despite being 6.5% below the prior year's record.
  • Like the Broader Economy, the High Tech Sector is Becoming Less Dynamic — The high-tech sector remains more dynamic than the rest of the economy, but the gap has faded as firm entry rates declined in both. The national firm entry rate peaked at 13.5% and the high-tech rate at 17.9%, and the gap between them narrowed from 5–6 percentage points to under one.
  • The Economics of Inequality in High-Wage Economies — United States Income, Wealth, Consumption, and Inequality Diana Furchtgott-Roth
  • Startups
  • Productivity

The Case For Continued American Equity Exceptionalism

AI Summary. Continued outperformance by US stocks is plausible because the US is positioned to capture a sizeable share of productivity gains from technologies such as artificial intelligence, while a moderating global economy would weigh on more cyclically oriented markets abroad. One study attributes 39% of 15-year equity returns to domestic economic performance.

Rebecca Patterson Financial Times
Date Posted:
August 4, 2023
Is Database:
Database

Rebecca Patterson argues US equity outperformance is likely to continue as US firms are positioned to capture a sizable share of productivity benefits from new technologies like AI, and the US is likely to experience stronger relative economic growth.

Will US stocks keep outperforming foreign markets?

Core argument: A 2011 study by Clifford Asness, Roni Israelov and John Liew suggests 39% of 15-year equity returns can be explained by domestic economic performance, consistent with the finding that domestic growth dominates local equity returns over multi-year periods.

American equity exceptionalism is possible, for at least two reasons. First, the US is set to capture a sizeable share of productivity benefits from technology such as artificial intelligence. Second, a moderating global economy could work against more cyclically biased equity markets overseas, favouring those geared towards organic growth drivers. Over multi-year periods, domestic growth has been found to dominate local equity returns. A 2011 study by Clifford Asness, Roni Israelov and John Liew suggests that 39% of 15-year returns could be explained by domestic economic performance. Growth is fundamentally a function of labour and productivity. Given that most of the developed world (and China) faces at least directionally similar labour constraints, the US seems likely to be a relative growth winner thanks to prospects for greater productivity gains.

Takeaways by Macro Roundup® AI

  1. A 2011 study by Clifford Asness, Roni Israelov and John Liew suggests 39% of 15-year equity returns can be explained by domestic economic performance, consistent with the finding that domestic growth dominates local equity returns over multi-year periods.
  2. The case for continued American equity exceptionalism rests on the US capturing a sizeable share of productivity benefits from technology such as artificial intelligence, and on a moderating global economy working against more cyclically biased overseas equity markets.
  3. With most of the developed world and China facing at least directionally similar labour constraints, the US seems likely to be a relative growth winner thanks to prospects for greater productivity gains.

Related Articles:

  • Market Resilience or Investors in Denial: The Market at Mid-Year 2023 — The S&P 500 rose 15.91% in the first half of 2023 and the tech-heavy NASDAQ returned nearly twice that, while the expected return on stocks fell from 9.82% to 8.81% and the implied equity risk premium slipped from 5.94% to 5%. The author argues that premium, roughly its average since 2008, does not signal a bubble.
  • Most Global Economies Remain in Disequilibrium, Requiring Policy Action — An investment framework holds that markets and economies are driven by three equilibriums — spending in line with output and capacity, incomes in line with debts, and normal risk premiums across assets — interacting with two policy levers, monetary and fiscal policy. When these conditions are absent, the resulting social, political, and business strains produce changes until equilibrium is restored.
  • Birth, Death, and Wealth Creation — The median age at which US companies went public rose from 7.9 years in 1976–2000 to 9.5 years in 2001–2022, implying that more wealth creation now occurs in private markets. Research on more than 28,000 US-listed companies since 1926 finds that just under 60% destroyed $9.1tn of wealth while about 2% created $50tn.
  • Growth
  • GDP

What’s the Matter With Miami?

AI Summary. A significant share of Florida's population inflow is retirees, and while the overall U.S. population grew 7.4% from 2010 to 2020, the population aged 65 and older grew 38.6%. Because retirees spend money on local services, the influx of seniors creates jobs for younger adults as well.

Paul Krugman Krugman Wonks Out
Date Posted:
August 4, 2023
Is Database:
Database

Florida’s growth relative to the population decline in Miami is driven by affordable housing and the baby boomers retiring. @paulkrugman notes that between 2010-20 the US population grew 7.4% but the share over age 65 grew 38.6%.

How does retiree migration drive local job growth?

Core argument: The U.S. population aged 65 and older grew 38.6% between 2010 and 2020, while the overall population grew 7.4%, creating a larger pool of potential retired migrants than in the past.

What are all those new Floridians doing for a living? Well, a significant number are retired. Retirees have been moving to Florida for the warm winters for a long time. But there are a lot more potential retired migrants now than in the past: between 2010 and 2020 the overall U.S. population grew only 7.4%, but the population 65 and older grew 38.6%. And since retirees spend money on local services, the influx of seniors creates jobs for younger adults as well.

Takeaways by Macro Roundup® AI

  1. The U.S. population aged 65 and older grew 38.6% between 2010 and 2020, while the overall population grew 7.4%, creating a larger pool of potential retired migrants than in the past.
  2. A significant number of Florida's new residents are retirees, continuing a long-standing pattern of migration to the state for its warm winters.
  3. Retirees moving to Florida spend money on local services, which creates jobs for younger adults as well.

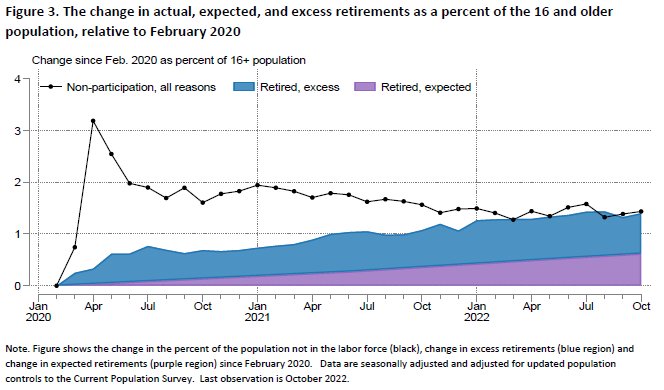
In October 2022, the retired share of the American population was 1½ percentage points above its pre-pandemic trend. These 3.5 million workers account for essentially all of the shortfall in labor force participation rates., “…Despite some improvement in the labor force participation rate for the working-age population since the early stages of the pandemic, the LFPR in October 2022 remained nearly 1½ percentage points below its pre-pandemic, February 2020 level (after making adjustments for changes in population weights introduced from the 2020 Census). The importance of retirements in accounting for this shortfall is illustrated in Figure 1, which shows the percentage of the working-age population that is not in the labor force for different reasons (black line) relative to February 2020, based on responses to the Current Population Survey. While earlier in the pandemic, factors other than retirements were an important contributor to elevated non-participation (such as non-participation while caregiving, the orange line), the percent of the population that was not in the labor force and retired (the “retired share”) has steadily increased and in October 2022 was almost 1½ percentage points above its pre-pandemic level, representing an increase of more than 3½ million retirees and accounting for essentially all of the total shortfall in the LFPR….”

Brandon Adams Comment: “This is a great paper. I think the labor force participation rate could converge toward its pre-pandemic trend line faster than envisioned in this paper. The paper ignores asset markets altogether, and it seems clear to me that rapidly inflating retirement accounts in 2021 was a big part of this story. Towards the tail end of the time period covered in this paper, retirees met the unwelcome duo of rapidly decreasing asset prices and rapidly increasing consumer prices. This might or might not bring people in their 60s or 70s out of retirement, but it will almost surely slow the exit rate of those aged 40-60, and it might also bring back into the labor force some people in that age range who are currently sitting out.”

The Evidence The pre-pandemic trend, “…Even in the absence of the pandemic, the retired share would likely have risen, albeit more gradually, due to shifts in the age distribution of the population toward ages traditionally associated with higher retired shares (primarily, the movement of the Baby Boomer cohort into older ages). As one illustration of the importance of population aging, Figure 2 plots the retired share (solid line) alongside a counterfactual trend (dashed line)….”

“…. This trend is an estimate of how the retired share would have evolved in the absence of the pandemic and is derived by assuming the continuation of pre-pandemic, age-specific trends in retired shares, assuming the state of the business cycle remained similar to pre-pandemic levels, and accounting for the actual changes in the age distribution over this period (in section III, we discuss in more detail the calculation of this and other counterfactual retired shares). Over the five years prior to the pandemic, the retired share increased about 0.2 percentage point per year, and plausibly would have continued increasing at a similar pace in the absence of the pandemic. As of October 2022, the retired share remained 0.6 percentage point above the pre-pandemic expected trend, or about 1.6 million people (Figure 2). This gap between the actual and expected lines is an estimate of “excess retirements,” and the excess retirements gap remains sizeable. In fact, the retired share was slightly below trend just prior to the pandemic (about 0.2 percentage point), implying that excess retirements as a share of the population have increased by about 0.8 percentage point since February 2020, or about 2.1 million people. That increase in excess retirements explains a little more than half of the 1.4 percentage point increase the total retired share since February 2020, whereas the increasing expected retired share explains the rest (see Figure 3)….”

“…Thus, less than half of the increase in the retired share to date would likely have occurred even in the absence of the pandemic, suggesting that more than half of the current LFPR shortfall is a direct result of the pandemic on retirement….First, as discussed above, more than half of the increase in the retired share relative to February 2020 is due to an increase that would have been expected in the absence of the pandemic. Second, about two-thirds of the total increase in the excess retired share is attributable to those who were age 65 and older at the start of the pandemic, with a particularly sharp increase in excess retirements among those age 70 and older. The remaining one-third of the increase in the excess retired share is attributable to those age 55 to 64 when the pandemic began. Third, there is also substantial heterogeneity across education, race, and ethnic groups, with retired shares for those age 65 and older increasing more than expected for Whites relative to Blacks and Hispanics, and for those with a college education relative to those without….…Because the retired share has remained significantly elevated since increasing substantially at the start of the pandemic and has shown little sign of converging towards its ex-pandemic counterfactual, it may take some years for retirement behavior to normalize relative to pre-pandemic norms and for the retired share of the population to converge toward what it would be in the absence of pandemic-related influences. We view it as unlikely, however, that the retired share will fall substantially towards its pre-pandemic trend and that those who retired early will return to the labor force in large numbers, since most of the excess retirements are concentrated among people who are 65 and older who (given their age) would likely be retiring in greater numbers anyway over the next few years. That assessment is supported by the stabilization of the unretirement rate at its pre-pandemic level, well below the level it would need to reach for the retired share to fall substantially…”

Joshua Montes, Christopher Smith, and Juliana Dajon, ” “The Great Retirement Boom”: The Pandemic-Era Surge in Retirements and Implications for Future Labor Force Participation,” Federal Reserve Board, November 2022, https://www.federalreserve.gov/econres/feds/the-great-retirement-boom.htm

Related Articles:

  • Miami Sees Its First Population Drop in Decades — Miami-Dade County lost 79,535 residents to net migration to other parts of Florida and other states over a recent multiyear stretch, an analysis of U.S. Census Bureau data by the Brookings Institution found, and the county's population shrank despite partial offset from foreign immigration. Miami home prices rose 53%.
  • A $100 Billion Wealth Migration Tilts US Economy’s Center of Gravity South — Six fast-growing Southern states — Florida, Texas, Georgia, North and South Carolina, and Tennessee — now contribute more to US GDP than the Northeast, including the Washington-New York-Boston corridor. The Southeast accounted for more than two-thirds of US job growth since the pandemic began, nearly double its pre-pandemic share, and housed 10 of the 15 fastest-growing large American cities.
  • Florida Ocean Temperatures At ‘Downright Shocking’ Levels — Much of Florida is recording its warmest year on record, with temperatures 3–5 degrees above normal and coastal waters in the Florida Keys reaching 92–96 degrees versus the more typical upper 80s. The National Oceanic and Atmospheric Administration reports about 40% of the world's oceans face a marine heat wave, the highest share on record.
  • Growth
  • GDP
    • Housing

Big Pharma's Big Tax Dodge

AI Summary. Six major US pharmaceutical firms reported $215bn in US sales versus $170bn abroad, yet attributed $90bn of their combined $100bn in profits to foreign operations and only $10bn to the US. That implies a 5% profit margin in the US and over 50% abroad.

Brad Setser and Tess Turner Business Insider
Date Posted:
August 4, 2023

.@Brad_Setser argues tax reform is needed as the American pharmaceutical sector has optimized its corporate structure to shift almost all of its domestic profits overseas paying an effective tax rate of 3%.

Do drug companies report most profits abroad despite higher US sales?

Core argument: Six major US pharmaceutical firms reported $90 billion of their $100 billion combined 2022 profit as earned abroad, leaving $10 billion attributed to US operations.

The six major US pharmaceutical firms that provide fairly detailed data reported making $215 billion worth of sales in the US for 2022. Given America's systematically higher prices, their sales abroad were logically more modest — totaling $170 billion. Despite this discrepancy, the companies reported earning very, very little in profits — in some cases, absolutely nothing — in the US. Of their $100 billion combined profit, the companies said $90 billion was made abroad, while a paltry $10 billion came from their US operations. That comes out to a profit margin of 5% in the US and a margin of over 50% abroad.

Takeaways by Macro Roundup® AI

  1. Six major US pharmaceutical firms reported $90 billion of their $100 billion combined 2022 profit as earned abroad, leaving $10 billion attributed to US operations.
  2. The six firms reported $215 billion in US sales against $170 billion abroad for 2022, a profit margin of 5% in the US versus over 50% abroad.
  3. Despite systematically higher US prices, the six pharmaceutical companies reported very little profit in the US, in some cases none at all.
  • Taxation
  • Fiscal Policy

Furman On Jobs Report

AI Summary. The unemployment rate fell to 3.5% and has stayed within a 3.4%–3.7% band for 17 consecutive months, while recovery in the age-adjusted participation rate has pushed the employment-population ratio for prime-age workers aged 25–54 above its pre-pandemic level. Average hourly earnings growth has picked back up from a 3.5% annual rate to about 5%.

Jason Furman @jasonfurman
Date Posted:
August 4, 2023
Is Database:
Database

While wages are still accelerating, @jasonfurman notes cooling jobs/hours and thinks today’s job report is consistent with a soft landing.

Is the labor market still tight as wage growth reaccelerates?

Core argument: Average hourly earnings growth has risen from a 3.5% annual rate earlier this year to 5%, unchanged since early 2022, reversing the earlier wage slowdown, though Furman notes these figures are noisy and subject to large revisions.

The unemployment rate fell back to 3.5%. Has been in a 3.4% to 3.7% band for 17 straight months. The last time this happened was Nov 2007. Given the recovery in the (age-adjusted) participation rate this has brought the employment-population rate for prime age workers (25-54) above the pre-pandemic rate. The wage growth slowdown earlier this year has largely gone away. Earlier this year average hourly earnings were growing at a 3.5% annual rate, now they're up to a 5% annual rate--unchanged since early 2022. Note, these are noisy and can be revised a lot. Overall this report is mixed for the inflation outlook: Jobs/hours: Cooling Unemployment rate: Neutral Wages: Heating I tend to think the order I listed them above is roughly right for what signals matter so think this report is slightly favorable for inflation.

Takeaways by Macro Roundup® AI

  1. Average hourly earnings growth has risen from a 3.5% annual rate earlier this year to 5%, unchanged since early 2022, reversing the earlier wage slowdown, though Furman notes these figures are noisy and subject to large revisions.
  2. Furman reads the report as slightly favorable for inflation, with jobs and hours cooling, the unemployment rate neutral, and wages heating, ranking those signals in that order of importance.
  • Wages/Income
  • Workforce
    • Unemployment/Participation


Loading More Posts

End of content

No more pages to load

© Copyright 2026 Coherent Research Institute · All Rights Reserved · Privacy · Terms