


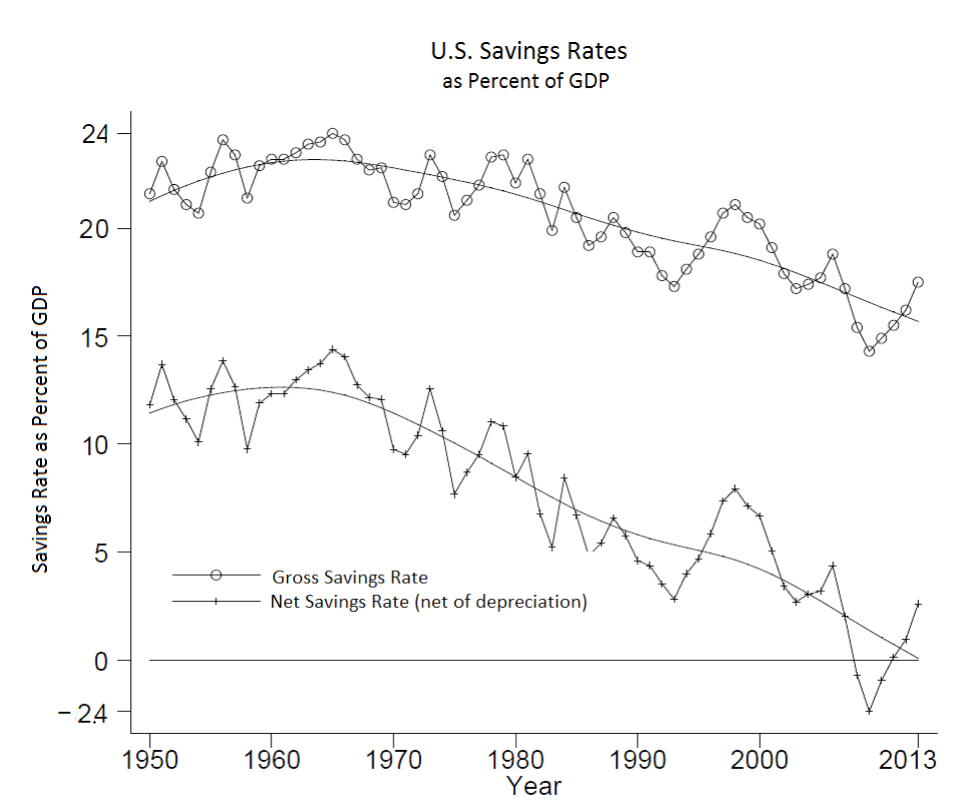
Alex Tabarrok reports on a recent paper by Per Krusell and Tony Smith that articulates the problem with Thomas Piketty’s so-called “Second Law of Capitalism” a problem that Larry Summers claims stems from Piketty “misreading the literature by conflating gross and net returns to capital.”
Krusell and Smith conclude: “We find Piketty’s second law quite misleading, and certainly not fundamental.”
Krusell and Smith reach this conclusion as follows:
“The second fundamental law…is rather implausible, for two reasons. … First … it implies savings behavior that, as the growth rate approaches zero, requires the aggregate economy to save 100% of GDP each year. Such behavior is clearly hard to square with any standard theories of how individuals save. … Second … the data speaks rather clearly against Piketty’s theory.”
“Though Piketty calls [the second law] an ‘accounting equation’, it really is a theory, because it builds in a certain form of savings behavior. It says that if the economy keeps the savings rate, s, constant over time, then the capital to income ratio k/y must, in the long run, become equal to s/g, where g is the economy’s growth rate…This formula is alarming because it suggests that were the economy’s growth rate to decline towards zero, as Piketty argues it will, capital’s share of income could increase explosively.1”
(“1 Piketty also argues that the return to capital is insensitive to how much capital is accumulated, so that capital’s share is driven largely by changes in k/y.”)
“In postwar U.S. data … with declines in growth, the net savings rate has fallen historically, and is currently actually already close to zero. … Decadal averages of savings rates and growth rates, [show] a clear positive relationship. … That s will remain constant and positive in the twenty-first century does not appear like a good assumption at all. … Projecting into the future based on Piketty’s second fundamental law, with g going to zero, appears unwise.”
“Did we miss something important? … His formulation of aggregate savings does not address … the central question of how net savings rates vary with growth rates. … Contrary to what Piketty suggests… [the] distinction between net and gross variables is quite critical for his interpretation. … It is not consistent with the textbook model as it is generally understood by macroeconomists.”
“We find Piketty’s second law quite misleading, and certainly not fundamental; we in fact think that the fundamental causes of wealth inequality are to be found elsewhere.”
P.S. Brad DeLong complains Krusell & Smith use an unrealistically high illustrative depreciation rate in their critique of Piketty’s “Second Law.” The rate is irrelevant to Krusell & Smith’s central point–that the mathematics underlying Piketty’s Second Law are farfetched—a point DeLong conspicuously avoids disputing. Krusell & Smith respond.